The second-hand market runs on trust between strangers.
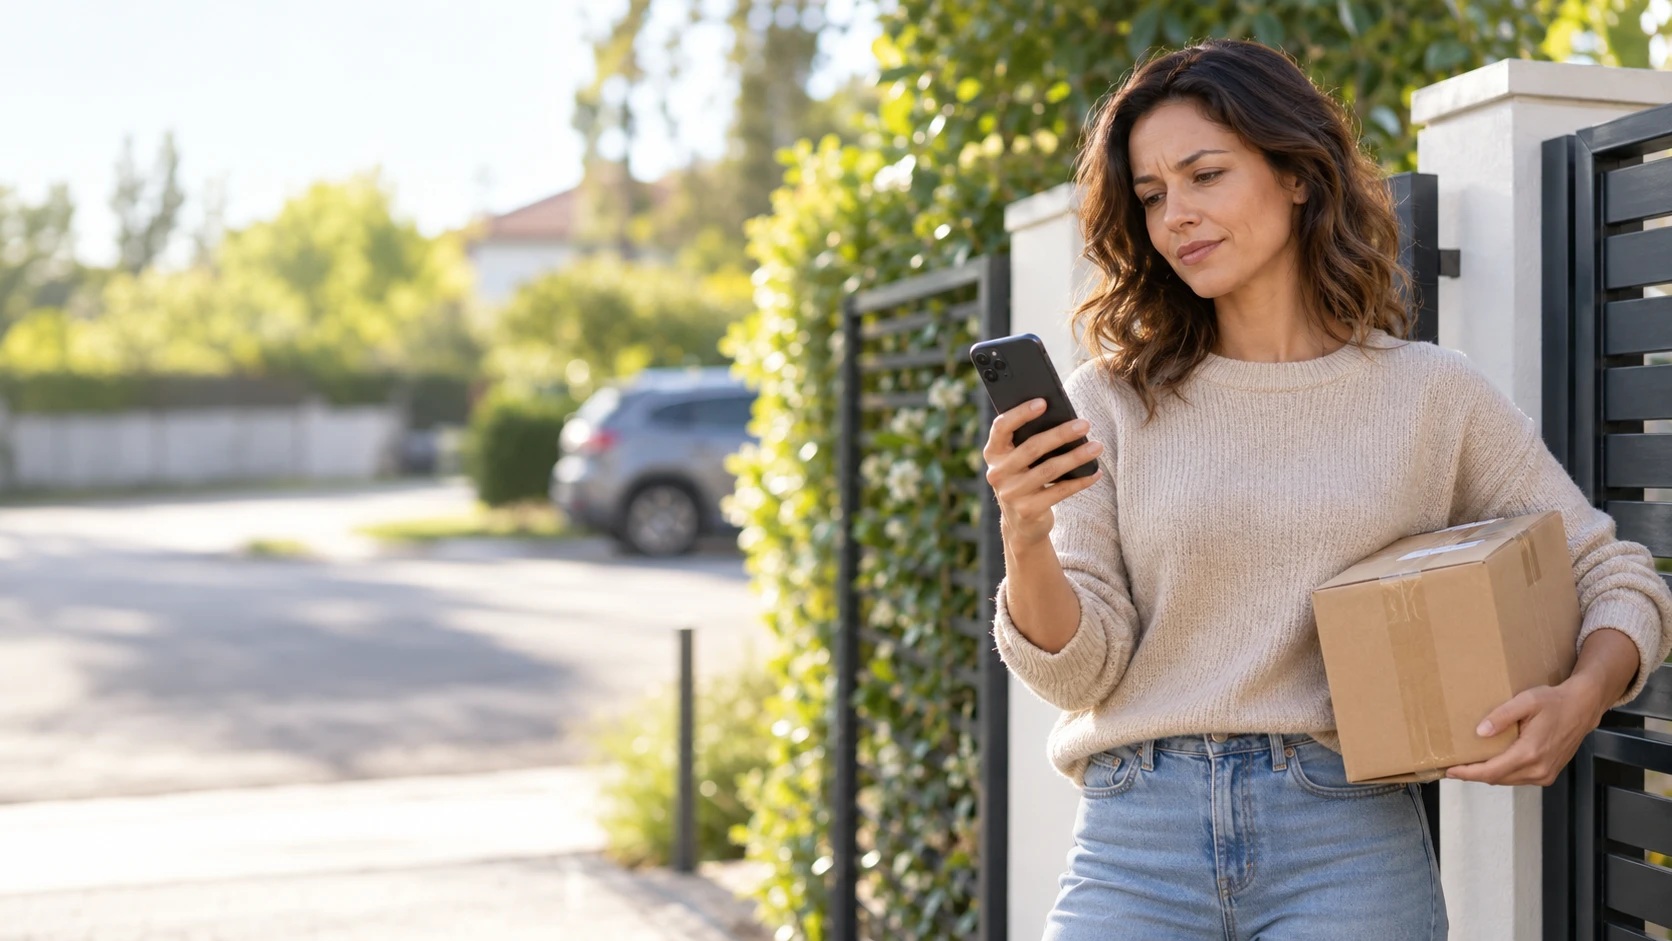
A buyer you have never met offers full price, “pays” immediately, and sends you a payment confirmation within minutes. Most of these sales end happily.
The ones that don’t almost always fail at the same point: the moment the seller accepts a document as if it were money.
The document is not the money
- A payment confirmation, whatever it looks like, is a record that a payment was initiated, not a promise that it will land. A standard bank transfer between accounts can take one to two business days to clear, and in that gap the confirmation already exists. Meanwhile the buyer is pressing you to hand over the phone, the couch, the puppy, “today, before I go away for work”.
That urgency is the tell. An honest buyer can wait for the money to show in your account. A dishonest one cannot, because the payment is fake, reversed later, or an overpayment that ends with you refunding the difference from your own pocket. The protective habit fits in one sentence: goods move when the balance moves. If you want to see exactly what a genuine confirmation document contains, where fake ones differ, and how the overpayment version of the scam works, there is a detailed guide to proof of payment and how to check it, written for South African sellers.
Payment method changes the waiting time, not the rule
Instant payment systems have shortened the waiting game: money sent with a phone number as the destination can arrive in seconds. That is convenient for honest buyers, and it also removes the “it’s the weekend” excuse from dishonest ones. Whatever the method, the rule does not change: you verify on your own screen, in your own account, never on theirs.
If the same person will pay you every month
Sellers sometimes graduate from one-off sales to steady arrangements: a buyer who takes fresh bread weekly, a parent paying for lift club every month. Regular payments from the same person deserve a regular setup, and the choice is between two instructions that look similar but are controlled by opposite people. A stop order is an instruction your payer gives to their bank to send you a fixed amount on a fixed date, and only the payer can change or cancel it. A debit order gives you, the recipient, permission to collect, which is a different relationship with different obligations. The difference between a stop order and a debit order matters for exactly this kind of arrangement, because it decides who has to chase whom when something changes.
The three habits that cover almost everything
- Verify on your own screen. Money visible in your account or app, not a screenshot, not a promise.
- Be suspicious of urgency and overpayment. Both exist to move your decision before your eyes do.
- Put repeating arrangements on a proper instruction. Handshake payments become disputes; instructions have dates, amounts and an owner.
Selling online is safe when the sequence is right: agree, wait, verify, release. The problems start when sellers are talked into doing it in a different order.